Keep the TSP
Review investment options, expenses, withdrawal flexibility, beneficiary rules, and access after separation.
 Padua Insurance Agency, LLC · License #L124739Padua Financial Services
Military & federal retirement education
Your TSP decision belongs inside a larger plan—one that considers military retirement, civilian employment, your spouse’s income, taxes, protection, and the life you want after service.
Honoring every branch
Educational resources for active-duty members, veterans, federal employees, and military families across all six branches.
Service emblems are shown solely to identify the six branches. All marks belong to their respective services. Padua Financial Services and Padua Insurance Agency, LLC are independent private businesses and are not affiliated with or endorsed by any military branch or the U.S. government.
Know the choices
Depending on your circumstances and plan rules, you may have several paths. We compare the practical benefits, restrictions, costs, taxes, and family considerations of each.
Review investment options, expenses, withdrawal flexibility, beneficiary rules, and access after separation.
Determine whether the plan accepts transfers and whether consolidation improves or limits your choices.
Compare investment flexibility, advice costs, creditor protection, distributions, and service.
Understand withholding, potential penalties, ordinary income tax, and the effect on long-term retirement security.
The income-stacking review
A new civilian salary can arrive while military retirement, VA benefits, a spouse’s wages, Social Security, and retirement withdrawals overlap. We map when each source begins and which items may affect taxable income.
Plain-English workshop
Designed for service members, veterans, and spouses who want to understand the financial decisions that arrive with a new career.
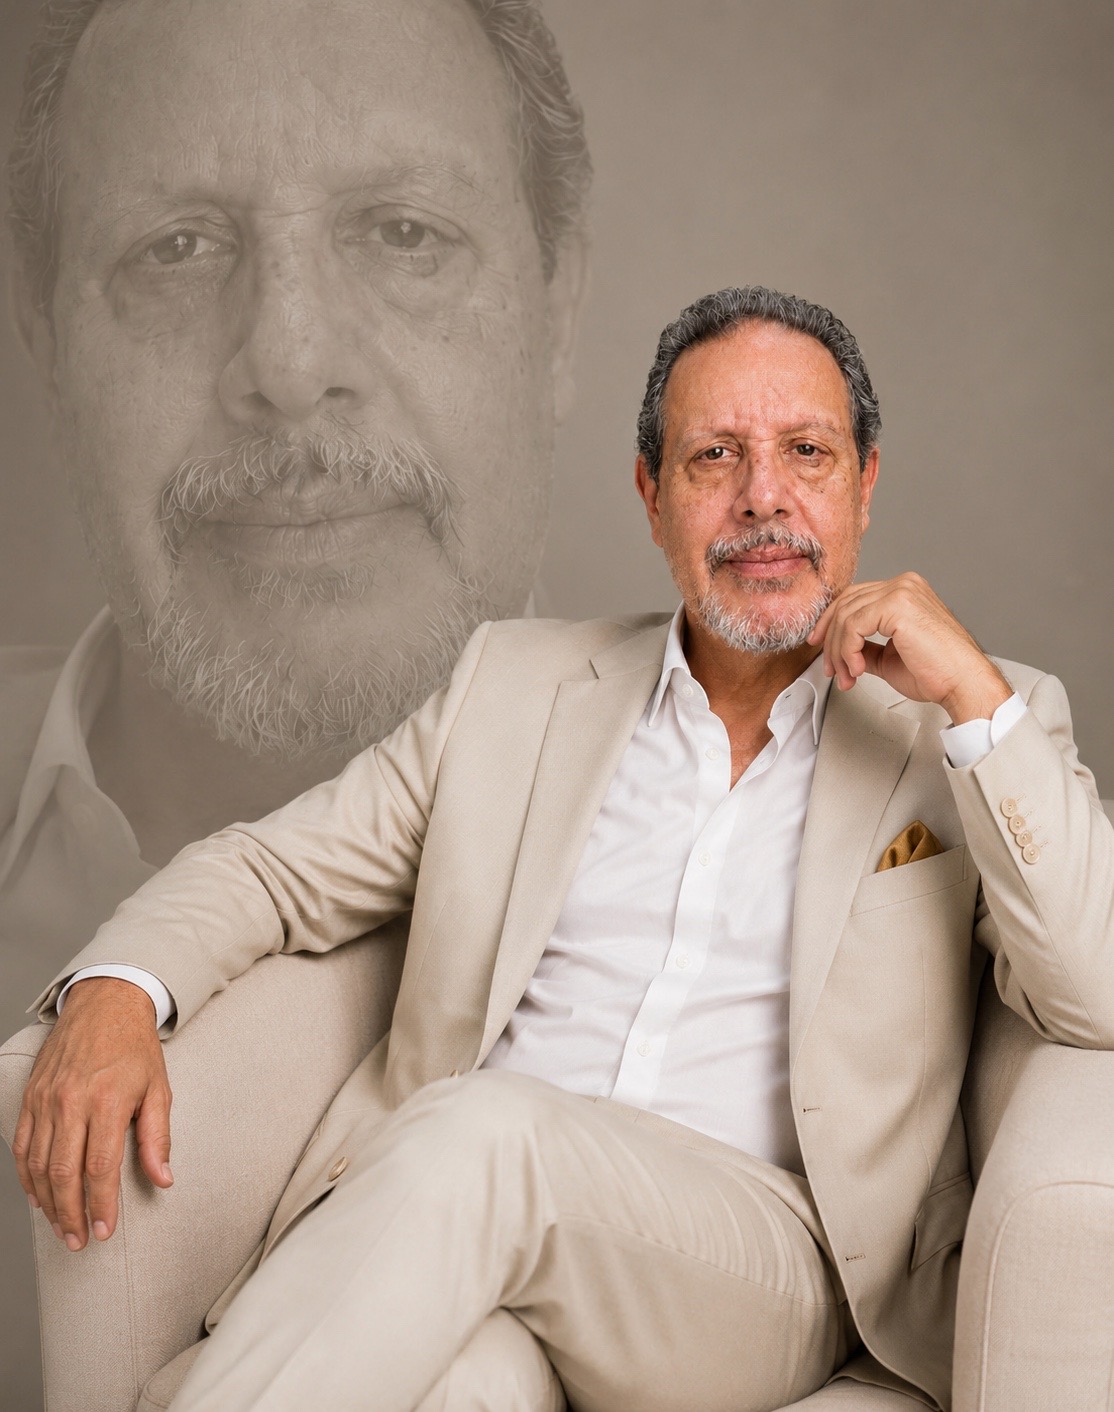
Florida, Texas, and Georgia Agent
FL #A198764 · TX #1660821 · GA #3482440
40+ years of tax and business experience.
Questions worth asking
Compare plan features, costs, protections, withdrawal choices, and access to professional guidance.
Identify advisory fees, fund expenses, insurance charges, surrender periods, and optional-benefit costs.
Review beneficiaries, survivor income, access to funds, and protection needs.
Discuss distributions, conversions, withholding, income stacking, and future RMDs with the appropriate tax professional.
Your next decision deserves a complete review
Padua Financial Services and Padua Insurance Agency, LLC are independent private businesses and are not affiliated with or endorsed by the Federal Retirement Thrift Investment Board, the U.S. government, or any military branch.
This material is educational and does not constitute individualized tax, legal, investment, or federal-benefit advice.
Insurance products are available only where properly licensed and appointed. Product guarantees depend on the claims-paying ability of the issuing insurer.